




Advertisement


CBN: Bold FX Reforms and Dollar Liquidity
By Zekeri Idakwo Laruba
There was a period in Nigeria when the search for dollars could become a seasonal ritual. As Christmas approached and Nigerians prepared to travel, demand for foreign exchange increased. Parents with children studying abroad worried about obtaining dollars for tuition and upkeep. Importers needed foreign currency to settle suppliers, businesses needed it for equipment and services, while travellers sought Personal Travel Allowance. Yet, obtaining dollars through official channels was often a challenge, forcing many legitimate users to look beyond the formal market.
The problem was not merely the exchange rate. It was the combination of price, availability and uncertainty.
For years, Nigeria’s foreign exchange system relied heavily on administrative intervention, official windows and allocation mechanisms intended to manage scarce foreign currency and protect the naira. At various points, the gap between the official and parallel markets became so wide that access to foreign exchange itself became a valuable privilege. The system could therefore produce an official rate that appeared attractive while legitimate users struggled to obtain dollars at that rate.
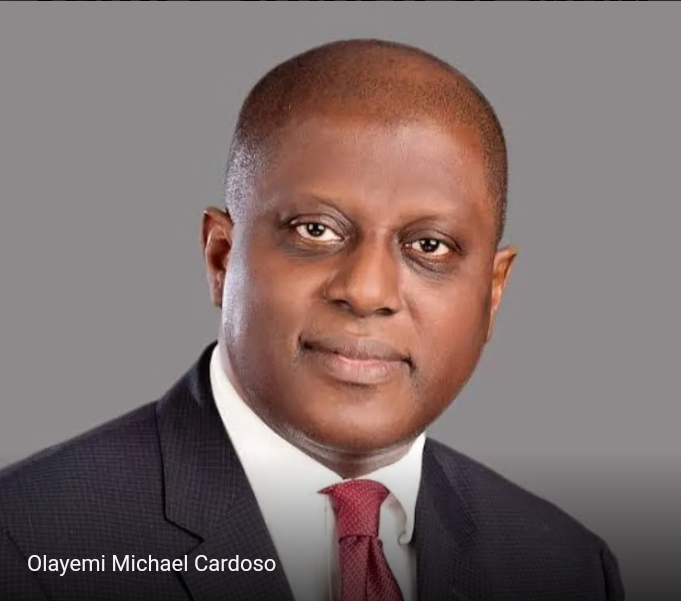
That was the environment inherited by the administration of President Bola Ahmed Tinubu in 2023, and it became one of the most consequential areas of economic reform undertaken by the Central Bank of Nigeria under Governor Olayemi Cardoso.
The turning point came on June 14, 2023, when the CBN announced the operational changes that effectively unified the foreign exchange market and moved the system towards a willing-buyer, willing-seller model. The objective was to allow market forces to play a greater role in price discovery, eliminate distortions created by multiple windows and improve transparency. The change was disruptive because it exposed pressures that had previously been suppressed, but it also marked a fundamental shift in how Nigeria approached the dollar.
The immediate consequences were painful. The naira depreciated sharply, imported goods became more expensive and inflationary pressures intensified. Businesses dependent on imported inputs faced higher costs, while households felt the impact through rising prices. For critics, the reform appeared to have traded one problem for another.
But the deeper question was whether Nigeria could build a foreign exchange market in which price and availability were determined by genuine demand and supply rather than administrative allocation.
The CBN subsequently embarked on a series of measures designed to improve liquidity, strengthen market discipline, clear outstanding obligations and restore confidence. The Monetary Policy Committee became an important platform for explaining this evolving policy direction because the foreign exchange market could not be separated from inflation, interest rates, reserves, liquidity and capital flows.
At its 293rd meeting on February 26–27, 2024, for example, the MPC raised the Monetary Policy Rate by 400 basis points, from 18.75 per cent to 22.75 per cent, while increasing the Cash Reserve Ratio for deposit money banks from 32.5 per cent to 45 per cent. The decision reflected the intensity of the inflation and exchange-rate pressures confronting the economy at the time.
The tightening continued. At the 294th MPC meeting on March 25–26, 2024, the committee raised the MPR again, from 22.75 per cent to 24.75 per cent, while retaining the CRR at 45 per cent. By May, at the 295th meeting, the MPR had reached 26.25 per cent. The sequence showed that the CBN was prepared to use monetary policy aggressively to prevent exchange-rate pressures from becoming entrenched in domestic prices.
The approach gradually shifted from emergency stabilisation to consolidation.
By September 2025, the MPC cut the MPR by 50 basis points to 27 per cent, its first reduction after the prolonged tightening cycle. At its November 24–25, 2025 meeting, the committee retained the rate at 27 per cent, signalling that the CBN believed the economy needed time for previous measures to transmit fully.
Governor Cardoso’s assessment at the November 2025 MPC was particularly revealing. He said the exchange rate had become “significantly less volatile” and had shown “a degree of market driven appreciation,” while stronger reserves and improved capital flows reflected structural changes resulting from the reforms.
The significance of that statement is that the CBN was no longer presenting stability as the result of simply defending a particular exchange rate. Instead, the emphasis was increasingly on creating conditions under which the market could function without constant central-bank intervention.
That transformation became even more evident in 2026. At the 304th MPC meeting of February 23–24, 2026, the CBN reduced the MPR by another 50 basis points to 26.5 per cent. In its communication, the Bank linked the continuing disinflation process partly to sustained exchange-rate stability, improved food supply and stronger balance-of-payments conditions.
The May 19–20, 2026 MPC meeting maintained the MPR at 26.5 per cent, while the CBN continued to emphasise the importance of preserving macroeconomic stability. The July 20–21 meeting also retained the rate at 26.5 per cent.
These decisions matter because monetary policy credibility and foreign exchange stability reinforce each other. When businesses and investors believe the exchange rate is less vulnerable to sudden policy reversals, speculative demand can moderate. When inflation expectations become better anchored, pressure on the currency can also ease.
But perhaps the clearest evidence of the changing FX market came from Cardoso himself in May 2026. Speaking at the launch of the fourth edition of the CBN Foreign Exchange Manual, the governor disclosed that average daily FX market turnover had risen from about $100 million when the Tinubu administration took office to between $400 million and $600 million. On some occasions, turnover had reached about $1 billion.
“When this administration took over, the average turnover per day was about $100 million. Today, it has increased to an average of between $400 million and $600 million daily,” Cardoso said.
He added that Nigeria had moved away from what he described as “a one-way market, where the central bank intervened and exited, and everybody waited for the next intervention,” towards “a more dynamic and open market.”
That may be one of the most important indicators of the reform story. A functioning foreign exchange market is not necessarily one in which the naira never depreciates. It is one in which buyers and sellers can participate, prices can adjust, transactions can be executed and liquidity can circulate without the entire system depending on occasional official intervention.
This is also where Bureau de Change operators have become increasingly relevant. In February 2026, the CBN authorised licensed BDCs to purchase up to $150,000 weekly from authorised dealer banks, subject to regulatory requirements, including Know-Your-Customer controls. The objective was to improve retail access while keeping the activity within a regulated framework. The policy also recognised that BDCs serve an important segment of the market, including travellers, students and other retail users of foreign currency.
The revised Foreign Exchange Manual, which took effect on June 1, 2026, further sought to simplify and harmonise procedures. It introduced clearer rules for travel allowances, import payments, service transactions, export proceeds and other FX operations. The CBN said the objective was to reduce ambiguity, strengthen compliance and make the market more transparent.
The response from market stakeholders has also been significant. Oliver Alawuba, Group Managing Director of United Bank for Africa and chairman of bank managing directors, described the revised manual as providing greater transparency, ethical conduct, stronger documentation and improved oversight. He said the reforms had brought “so much greater confidence in the Nigerian economy” and pledged that banks would support implementation.
For ordinary Nigerians, however, the ultimate test is not the language of monetary policy. It is whether the reform changes their everyday experience.
Consider the Nigerian parent paying international school fees. Under the old system, the challenge could involve obtaining approval, waiting for allocation or turning to alternative markets. Today, although the dollar remains expensive and exchange-rate movements remain a concern, the policy direction is towards making legitimate FX transactions more predictable and accessible through banks and regulated BDCs.
The same applies to businesses. A manufacturer may still complain about the cost of imported machinery or raw materials, but a transparent market allows the business to plan around a visible price rather than an uncertain allocation. An importer can price goods more rationally. A traveller can approach regulated channels. A student abroad can have greater certainty about tuition payments.
This is why describing the reform simply as a “strong naira” or “weak naira” story misses the bigger picture. The more fundamental change is from scarcity and administrative allocation towards liquidity, price discovery and market participation.
That does not mean every problem has disappeared. The naira remains exposed to oil prices, capital flows, external shocks, domestic demand and inflation. The market can still experience periods of thin liquidity and volatility. The CBN itself remains responsible for ensuring that market reforms do not become an invitation for manipulation, speculation or regulatory abuse.
Indeed, the CBN’s 2026 Foreign Exchange Manual and its continuing engagement with banks and BDCs show that market liberalisation is being accompanied by stronger rules, monitoring and compliance.
The journey, therefore, is not from intervention to complete non-intervention. It is from opaque and distortionary intervention towards a rules-based market in which the CBN provides the regulatory framework while legitimate buyers and sellers increasingly determine prices.
That is a profound shift from the experience of previous years. The dollar has not suddenly become cheap. But the dollar market is becoming less defined by the old question, “Where can I find dollars?”, and increasingly by the more normal market question, “At what price can I obtain dollars through a legitimate channel?”
For parents paying international school fees, businesses importing equipment, travellers preparing for foreign trips and regulated BDCs serving retail customers, that distinction is not merely technical.
It is the difference between a currency market dominated by scarcity and one increasingly organised around access. And perhaps that is the clearest measure of how far the CBN’s FX reforms have come.
Zekeri Idakwo Laruba is an Editor Economic Confidential, Fact-checker at PRNigeria and Coordinator PRNigeria Fellowship.
[email protected]


