


Brazil’s new curtailment rules offer greater regulatory certainty for solar developers, but uncertainty over future generation cuts and financial risks continues to weigh on investment. Industry experts expect new utility-scale solar projects to remain limited despite progress on compensation and curtailment allocation.
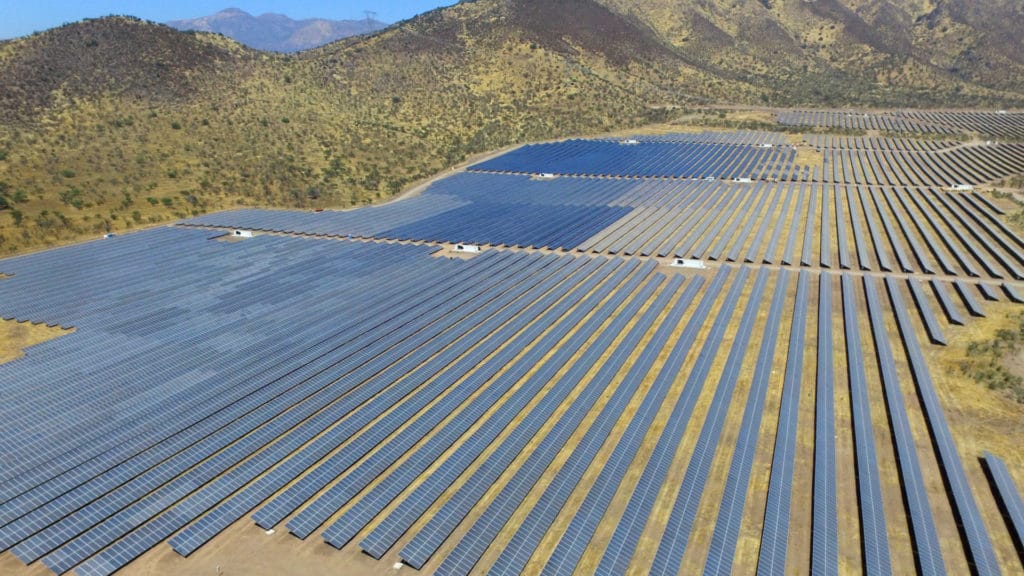
Large-scale solar developers in Brazil have received two updates on past and future generation curtailment. Curtailment rates of around 25%, combined with uncertainty over compensation, have frequently been cited as reasons for developers to surrender project authorizations. While the new curtailment rules offer greater certainty and predictability, a recovery in investment will depend on other factors.
In 2026 alone, developers surrendered authorizations for 923 solar projects in Brazil, representing more than 40.6 GW of capacity and BRL 134 billion ($26.3 billion) in lost investment, according to a study by the Brazilian Solar Photovoltaic Energy Association (ABsolar). The association said the figures show that curtailment, along with the lack of clear criteria for classifying curtailed energy and determining compensation, has become a decisive factor in investment decisions, even in regions with little history of curtailment.
The pace of authorization cancellations has accelerated since 2025, shrinking the pipeline of projects available for future capacity expansion. Data from Brazilian electricity regulator Aneel show that 2,492 power plants, with a combined potential capacity of 110 GW, held authorizations in January 2026. That figure has since fallen to 60 GW.
Solar generation curtailment reached an average of 1.4 GW in 2026, equivalent to 25.3% of total solar generation during the period. The volume of curtailed electricity is already approaching the total recorded for the whole of 2025.
Compensation and curtailment rules
The risk of curtailment and uncertainty over compensation have brought investment in new utility-scale solar projects to a standstill. In July, Brazil’s Ministry of Mines and Energy issued Ordinance 140, establishing compensation rules for curtailment between Sept. 1, 2023, and Nov. 25, 2025. A total of 682 solar power plants, with approximately 25.5 GW of installed capacity, are eligible for compensation.
According to ABsolar, the main question is whether the compensation will be sufficient to allow companies to resume investment, meet financing obligations and restore their financial positions. “If the agreement is signed, companies will drop any ongoing legal actions in which they are seeking compensation for these curtailments, regardless of how the curtailments are classified,” the association said.
Absolar noted that the compensation proposal excludes curtailment caused by electricity oversupply, which already accounts for most curtailment events. Nevertheless, the ordinance offers some predictability over potential compensation. “With this proposal in hand, companies can engage in financial planning and, crucially, negotiate the restructuring of project-related debt with their banks,” the association said.
Meanwhile, Aneel published the outcome of Public Consultation 45 last week, formalized through Normative Resolution 1,170 on Oct. 6. The resolution establishes how future curtailment will be allocated among different generation technologies. The long-awaited clarification is expected to provide greater predictability for new investment in the sector.
Resumption of investment depends on other factors
Although the outcome of Public Consultation 45 (CP 45) provides greater clarity on how energy-related curtailment will be allocated and reduces regulatory uncertainty, the new rules alone are unlikely to trigger a significant wave of new greenfield wind and solar projects, Eduardo Tobias, founding partner of Watt Capital, told pv magazine Brasil.
However, the introduction of a curtailment priority order, which includes run-of-river hydropower plants and prioritizes higher-cost generation sources, is expected to reduce the share of energy-related curtailment allocated to wind and solar plants.
“Now that the allocation rules are clear, we still need to estimate the volume of energy-related curtailment in the future. In other words, we know how the ‘pie’ will be divided, but it remains difficult to estimate how big the ‘pie’ will be,” Tobias said.
That calculation depends on several factors, including growth in electricity supply, energy storage deployment, demand-response measures, electricity demand growth, gross domestic product (GDP) growth and electrification. The interaction of these variables makes it difficult to forecast how much curtailment individual projects will face over the long term.
Beyond estimating curtailment volumes, developers also face challenges in forecasting the Settlement Price for Differences (PLD), which determines the financial impact of curtailment on generators’ revenue. Because the price is not determined through bidding and its calculation rules change frequently, the combination of uncertain curtailment volumes and PLD fluctuations makes project risk assessments even more complex.
Against this backdrop, Tobias expects new greenfield wind and solar projects to remain the exception rather than the rule for an extended period.
“I see some room for new solar projects located close to electricity demand, with or without batteries,” Tobias said. “When generation is located close to demand, consumers avoid curtailment, transmission system usage charges (TUST), losses up to the system’s reference point and the allocation of capacity reserve charges (ERCAP).”
More curtailment on the horizon
Brazil’s National Electric System Operator (ONS) is also developing plans to introduce controls for distributed generation. As distributed generation (DG) continues to expand, industry representatives are calling for economic and regulatory incentives to make some small-scale distributed generation resources dispatchable.
One proposal involves encouraging consumers to invest in battery storage systems to absorb surplus generation and reduce the need for curtailment.
To help establish the necessary procedures, Absolar is preparing a study on the conditions for implementing distribution system operators (DSOs) and managing distributed generation. The study will focus on technical requirements, governance and transparency.
The association argues that these decisions should not be left solely to distribution utilities. Instead, it advocates the involvement of independent entities in managing distributed generation to improve economic efficiency.
This content is protected by copyright and may not be reused. If you want to cooperate with us and would like to reuse some of our content, please contact: [email protected].


