




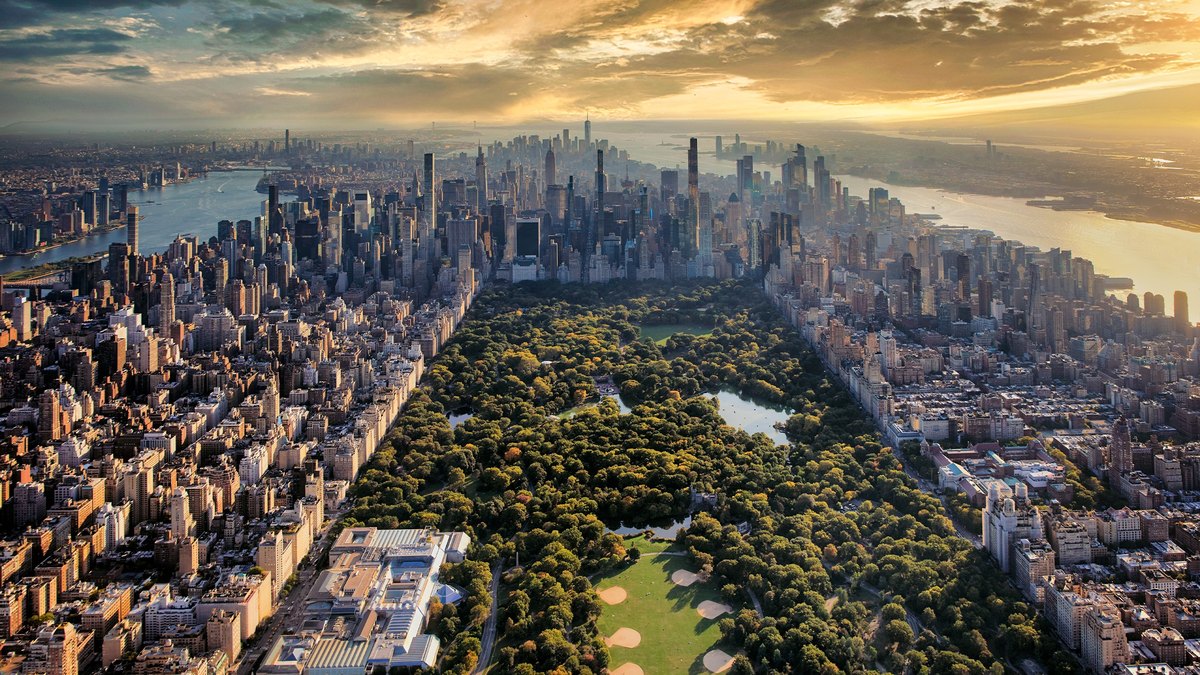
The Manhattan luxury market is booming despite the Big Apple’s looming pied-à-terre tax on second homes valued over $1 million.
Last week, 36 contracts were signed at $4 million and above, eight more than the previous week and the most since the first week of June, according to the Olshan luxury report.
The Upper East Side took the crown for the most popular area, and condos outsold co-ops—as they normally do. But this time, the gap between them was considerably smaller, with 19 condos sold, only six more than co-ops.
Co-ops not only tend to be a lot older than condos, but require an often-onerous board approval process. However, they are typically cheaper. The average asking price of a co-op at the luxury level last week was $6.8 million versus $9.4 million for a condo.
The top-selling property was a six-bedroom penthouse condo at 255 East 77th St. with an asking price of $23.75 million, or $4,303 per square foot.
A major lure here is no doubt the sweeping 36-degree views of Central Park from nearly all the rooms and the two terraces totaling 363 square feet. A six bedroom condo at this size—5,520 square feet—is rare, and the unit took only five months from listing to contract.
The Robert A.M. Stern Architects–designed building includes amenities such as a door attendant, concierge service, lounge, children’s playroom, golf simulator, library, and automated parking system. The fitness center boasts a yoga room, spa with steam room and sauna, massage/treatment room, and the crown jewel: a 75-foot swimming pool.
Alexa Lambert of Compass held the listing.
Last week’s second top sale, a sponsor condo at 53 W. 53rd St., had an asking price of $21.53 million. The 3,762-square-foot, three-bedroom unit, with north-facing views of Central Park, was sold on the same day it was listed, indicating it could have been an off-market deal.
Luxury buyers shrug at new tax
The strong luxury market belies warnings that it would collapse after the pied-à-terre tax became effective on July 1.
For secondary-home condos and co-ops with a fair market value of $1 million to $3 million, the surcharge rate is 4.00%. For $3 million to $5 million, it is 5.25%, and for $5 million or greater, it is 6.50%. (Currently, the tax is collected annually and set to end on June 30, 2031.)
The rollout has been fraught with delays and legal challenges, and about 55% of those hit with a tax bill have thus far successfully appealed, according to The City.
Michael Reisor of the Compass-affiliated Reisor Team, who recently sold a $4.5 million loft condo at the Schumacher complex on Bleecker Street in Noho that will be used as a pied-à-terre, says the upcoming levy isn’t stopping the wealthy from investing in Manhattan.
“Every type of product in Manhattan is only going to be getting more expensive as time goes on,” he tells Realtor.com®. “New York will always be New York. If you’re waiting out news on the pied-à-terre tax, you’re going to be waiting too long, and you won’t be able to catch up with the market.”
Nor is New York City the only area seeking to increase taxes on the rich. Whether it’s California‘s proposed Billionaire Tax or Washington‘s Millionaires Tax (effective January 2028), states looking to top off their coffers by taxing the wealthy in one form or another are increasing, leaving elite buyers with less choice on where to live if they want to avoid higher taxes.
“We’re not seeing people not purchase the product they want because of fears of the tax, and the numbers this week reflect that,” says the broker. “No one is going to throw out New York because of taxes.”
Reisor says buyers might adjust their budget a little. But most affluent buyers would rather not dial down their lifestyle (and major asset), preferring instead to adjust their budget in other ways if needed.
He points to one client, owner of a pied-à-terre townhouse, who looked for something less expensive due to the new tax, but decided against it, preferring a property that met his wishes and standards.
Wealthy buyers “kind of poke their heads above water, look around, and go, ‘Eh, I’ll deal with the tax,'” says Reisor. “There’s a price to being in Manhattan, one that people deem worth it.”
Michelle Griffith of Douglas Elliman, who brought the buyer the city’s second top sale two weeks ago, tells Realtor.com that luxury agents “are all sort of surprised by the strength of the luxury market.”
Griffith puts the robust market down to two factors: lack of inventory and the exorbitant rental market.
“This is lack of inventory across all price points,” she says. “You couple that with rents that are through the roof. That takes people who are living and working in Manhattan, with the kids in school, and pushes them into buying scenarios.”
She says high-end apartments that would have previously rented for $25,000 a month are now entering bidding wars and going for near double that. Those who don’t want to pay crushing monthly rents are forced into a buying market with slim inventory.
“For the longest time, people were saying ‘Let’s wait for more inventory to come on the market,'” she says, noting it is down almost 30% this fall. “We don’t see new inventory.”
She adds: “We’re saying to our clients, ‘Listen, there is no perfect apartment. If it checks 7 out of the 10 boxes, you need to move forward with it.'”
The broker also notes that buyers who had previously held out for turnkey apartments have changed their minds as their dream apartments failed to materialize.
“Those [turnkey] properties have disappeared,” she says. “A lot of buyers are now saying, ‘I’m not afraid to renovate. I’ll take on a project.'”
Buyers are also willing to put in the renovations for their desired neighborhood, specifically the Upper East Side.
The high number of prewar co-ops that moved last week underscores that buyers are willing to take on renovations to get what they really want: prime location, layouts over 4,000 square feet, and at least three bedrooms.
The highest-selling co-op, a 1925 five-bedroom at 860 Park Ave. with an ask of $10,950,000, is described as “impeccably maintained,” and co-ops at the ultraluxury (top 1%) tier, which in the borough starts at approximately $5.6 million, generally will not need much, if any, work.
But Griffith says high-end buyers on the whole are more willing to take on a project, provided the property checks a certain amount of boxes. For the right size, layout and location, they’ll hire that contractor.
“It’s showing long-term commitment to Manhattan,” she says.
Get real estate news in your inbox
Kiri Blakeley writes about trending news at Realtor.com. She has also worked at Forbes Magazine, Forbes.com, CafeMom, and DailyMail.com, covering everything from billionaires to celebrities to crime. Her work can be found in news outlets worldwide, including Yahoo, SF Gate, New York Post, Seattle-Post Intelligencer, Marie Claire, She Knows, Huffington Post, and New York Magazine. She has an M.A. in journalism from Columbia University. In her spare time, she writes psychological thrillers under a pen name. She lives in Brooklyn, and her cat foster Instagram account has over 4 million views.


