
Advertisement

CBN Rate Cut: When Stability Begins to Reach the Real Economy, by Kabir AbdulSalam
For a small business owner who has watched the cost of borrowing rise, a reduction in the Central Bank of Nigeria’s benchmark interest rate is more than a figure announced after a Monetary Policy Committee meeting. It raises a practical question: will the cost of obtaining credit finally begin to fall?
For a manufacturer struggling with working capital, a farmer seeking seasonal financing, a trader trying to expand inventory or a young entrepreneur looking to invest in equipment, the significance of monetary policy is ultimately measured not in basis points but in whether finance becomes more accessible and economic activity becomes easier to sustain.
That is the broader significance of the CBN’s decision to cut its Monetary Policy Rate from 26.5 per cent to 23 per cent.
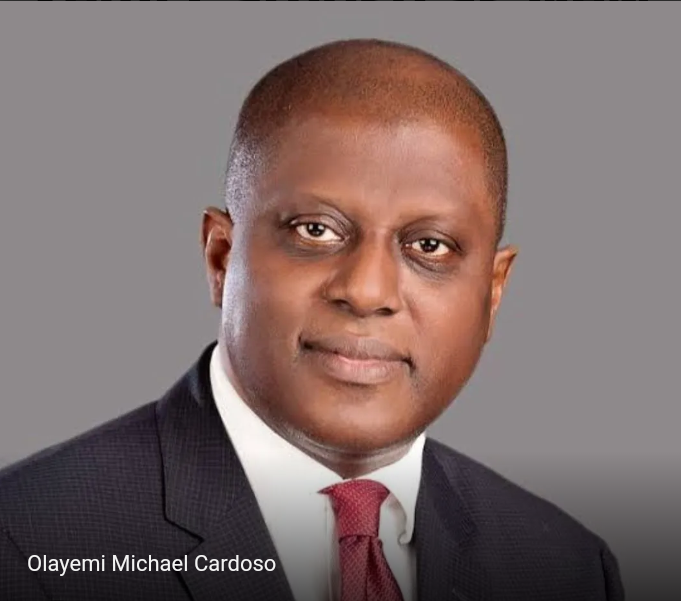
The September 21–22, 2026 meeting of the Monetary Policy Committee marked a new phase in the monetary reforms being implemented under CBN Governor Olayemi Cardoso. After a prolonged period of monetary tightening aimed at restoring price and financial stability, the latest decision suggests that the bank sees sufficient improvement in key economic indicators to begin creating more room for productive activity.
The 350-basis-point reduction was accompanied by a recalibration of the Standing Facilities Corridor to +50/-300 basis points around the new MPR. The CBN retained existing cash reserve requirements at 45 per cent for deposit money banks, 16 per cent for merchant banks and 75 per cent for non-TSA public-sector deposits.
The policy is therefore not simply a broad release of liquidity. Rather, the MPC described it as an operational recalibration designed to strengthen monetary-policy transmission and restore the MPR’s effectiveness as the principal signal for financial-market conditions.
That distinction is important because the success of the rate cut will ultimately depend on what happens beyond the CBN’s policy statement.
For manufacturers, lower market interest rates could reduce the financing burden associated with working capital, machinery and expansion, provided commercial lending rates respond accordingly. For small and medium-sized enterprises, improved access to credit could support inventory purchases, business expansion and employment.
The agricultural sector could also benefit if financing becomes more affordable for farmers, processors and agribusinesses, particularly because the cost of credit is only one part of the production equation. Energy, transportation, storage and input costs remain significant determinants of food prices.
In the housing and construction sectors, lower financing costs could improve the economics of mortgages, property development and infrastructure-related investment, although the transmission would depend on how quickly commercial lending rates adjust.
For consumers, however, the impact is likely to be less immediate. A lower MPR does not directly reduce food prices, transport fares or energy costs. Its potential benefit comes through the wider economy—lower financing costs, stronger investment, increased production and, if sustained, greater employment and purchasing power.
This is why the economic indicators preceding the decision matter.
Headline inflation declined from 15.43 per cent in July to 15.39 per cent in August 2026, while food inflation fell from 20.31 per cent to 19.57 per cent. Core inflation also moderated, according to the MPC.
Economic growth has simultaneously strengthened. Real GDP expanded by 4.43 per cent in the second quarter of 2026, compared with 3.89 per cent in the previous quarter. The non-oil sector grew by 4.31 per cent, while oil-sector growth accelerated to 7.31 per cent.
Business activity also remained in expansion territory, with the Purchasing Managers’ Index rising from 51.1 points in July to 52.7 points in August.
The external position has provided another layer of confidence.
The MPC reported gross external reserves of $55.25 billion as of September 18, sufficient to cover approximately 11.3 months of imports of goods and services. The balance-of-payments surplus rose from $2.38 billion in the first quarter to $3.51 billion in the second quarter, while the current-account surplus increased from $4.49 billion to $7.54 billion.
These developments provide important context for Cardoso’s reform agenda, which has sought to address monetary and foreign-exchange distortions while rebuilding confidence in the Nigerian economy.
The governor has previously highlighted the burden of accumulated Ways and Means financing and extensive interventions that contributed to excess liquidity. He has also argued that the former multiple foreign-exchange-rate regime created significant economic distortions.
The subsequent reform programme has focused on restoring monetary-policy credibility, improving foreign-exchange-market functioning and rebuilding external buffers.
The latest rate cut suggests that the CBN is now seeking to move from stabilisation towards transmission, ensuring that the gains achieved at the macroeconomic level begin to support productive sectors more directly.
This is where the banking sector becomes particularly important.
A reduction in the MPR does not automatically compel commercial banks to reduce lending rates by the same margin. Banks still price loans according to their funding costs, liquidity, credit risks, operating expenses and expected returns.
The CBN’s recalibration of the Standing Facilities Corridor and its adoption of the Nigerian Overnight Financing Rate as a transaction-based operational benchmark are therefore significant. The objective is to ensure that monetary-policy decisions communicate more effectively through the financial system.
If the transmission mechanism improves, sectors that depend heavily on credit could gradually experience more favourable financing conditions.
The CBN, however, must balance that objective with the need to prevent inflationary pressures from returning. The MPC has retained substantial cash reserve requirements and identified geopolitical tensions, global energy prices and election-related spending as potential risks to the inflation outlook.
The Federal Government’s fiscal position will also matter. Greater coordination between fiscal and monetary authorities is essential because fiscal expansion, public-sector liquidity and monetary conditions can influence inflation and interest rates in opposite directions.
The fiscal-monetary coordination framework between the Federal Ministry of Finance and the CBN therefore has an important role to play in maintaining policy consistency while preserving the central bank’s mandate for price and financial stability.
For Nigerians, the ultimate measure of the current reform cycle will not be the MPR itself. It will be whether greater macroeconomic stability gradually translates into lower financing costs, stronger businesses, increased production, more employment and improved household purchasing power.
The latest indicators suggest that Nigeria is entering that next stage from a stronger foundation than it had during the period of severe monetary and foreign-exchange instability.
The 23 per cent MPR should therefore be viewed within that wider trajectory: not as an instant solution to the cost-of-living challenge, but as part of the CBN’s effort to consolidate stability and create greater room for the productive economy to grow.
For businesses and households, the expectation is straightforward: that the hard-won stability at the macroeconomic level will increasingly be felt in everyday economic life.
Kabir Abdulsalam is a senior correspondent at Image Merchants Promotion Limited: [email protected]
